

The SRA accountants reports 2027 checklist starts with a clear distinction: January’s accounting-period collection and the new April reporting regime are separate tasks. Legal cashiers and finance colleagues can prepare the records. They should also identify who reviews them and who is authorised to submit the January form.
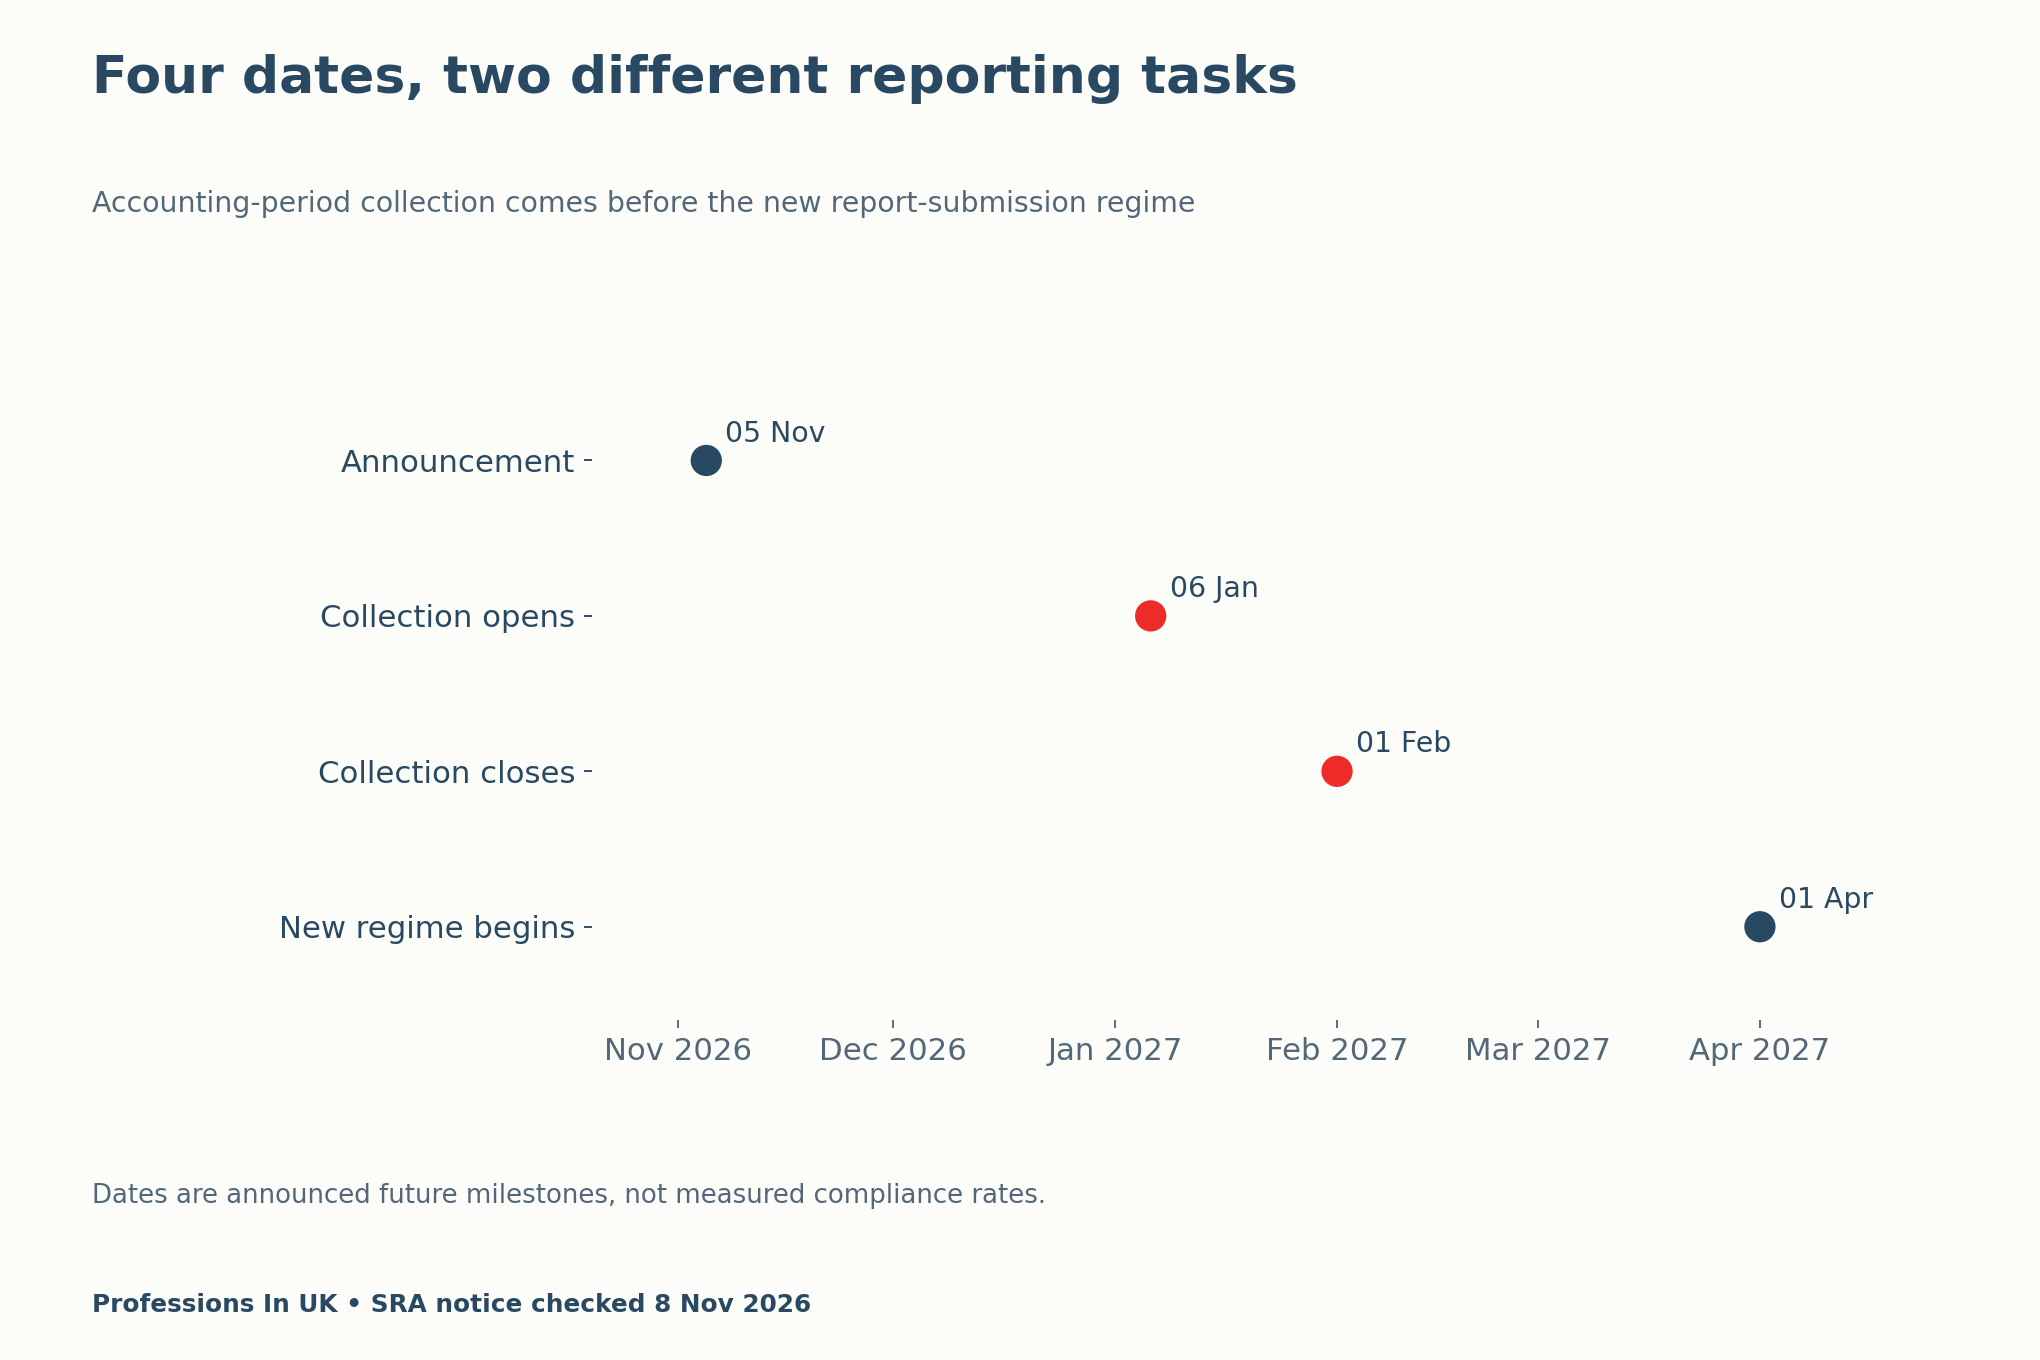
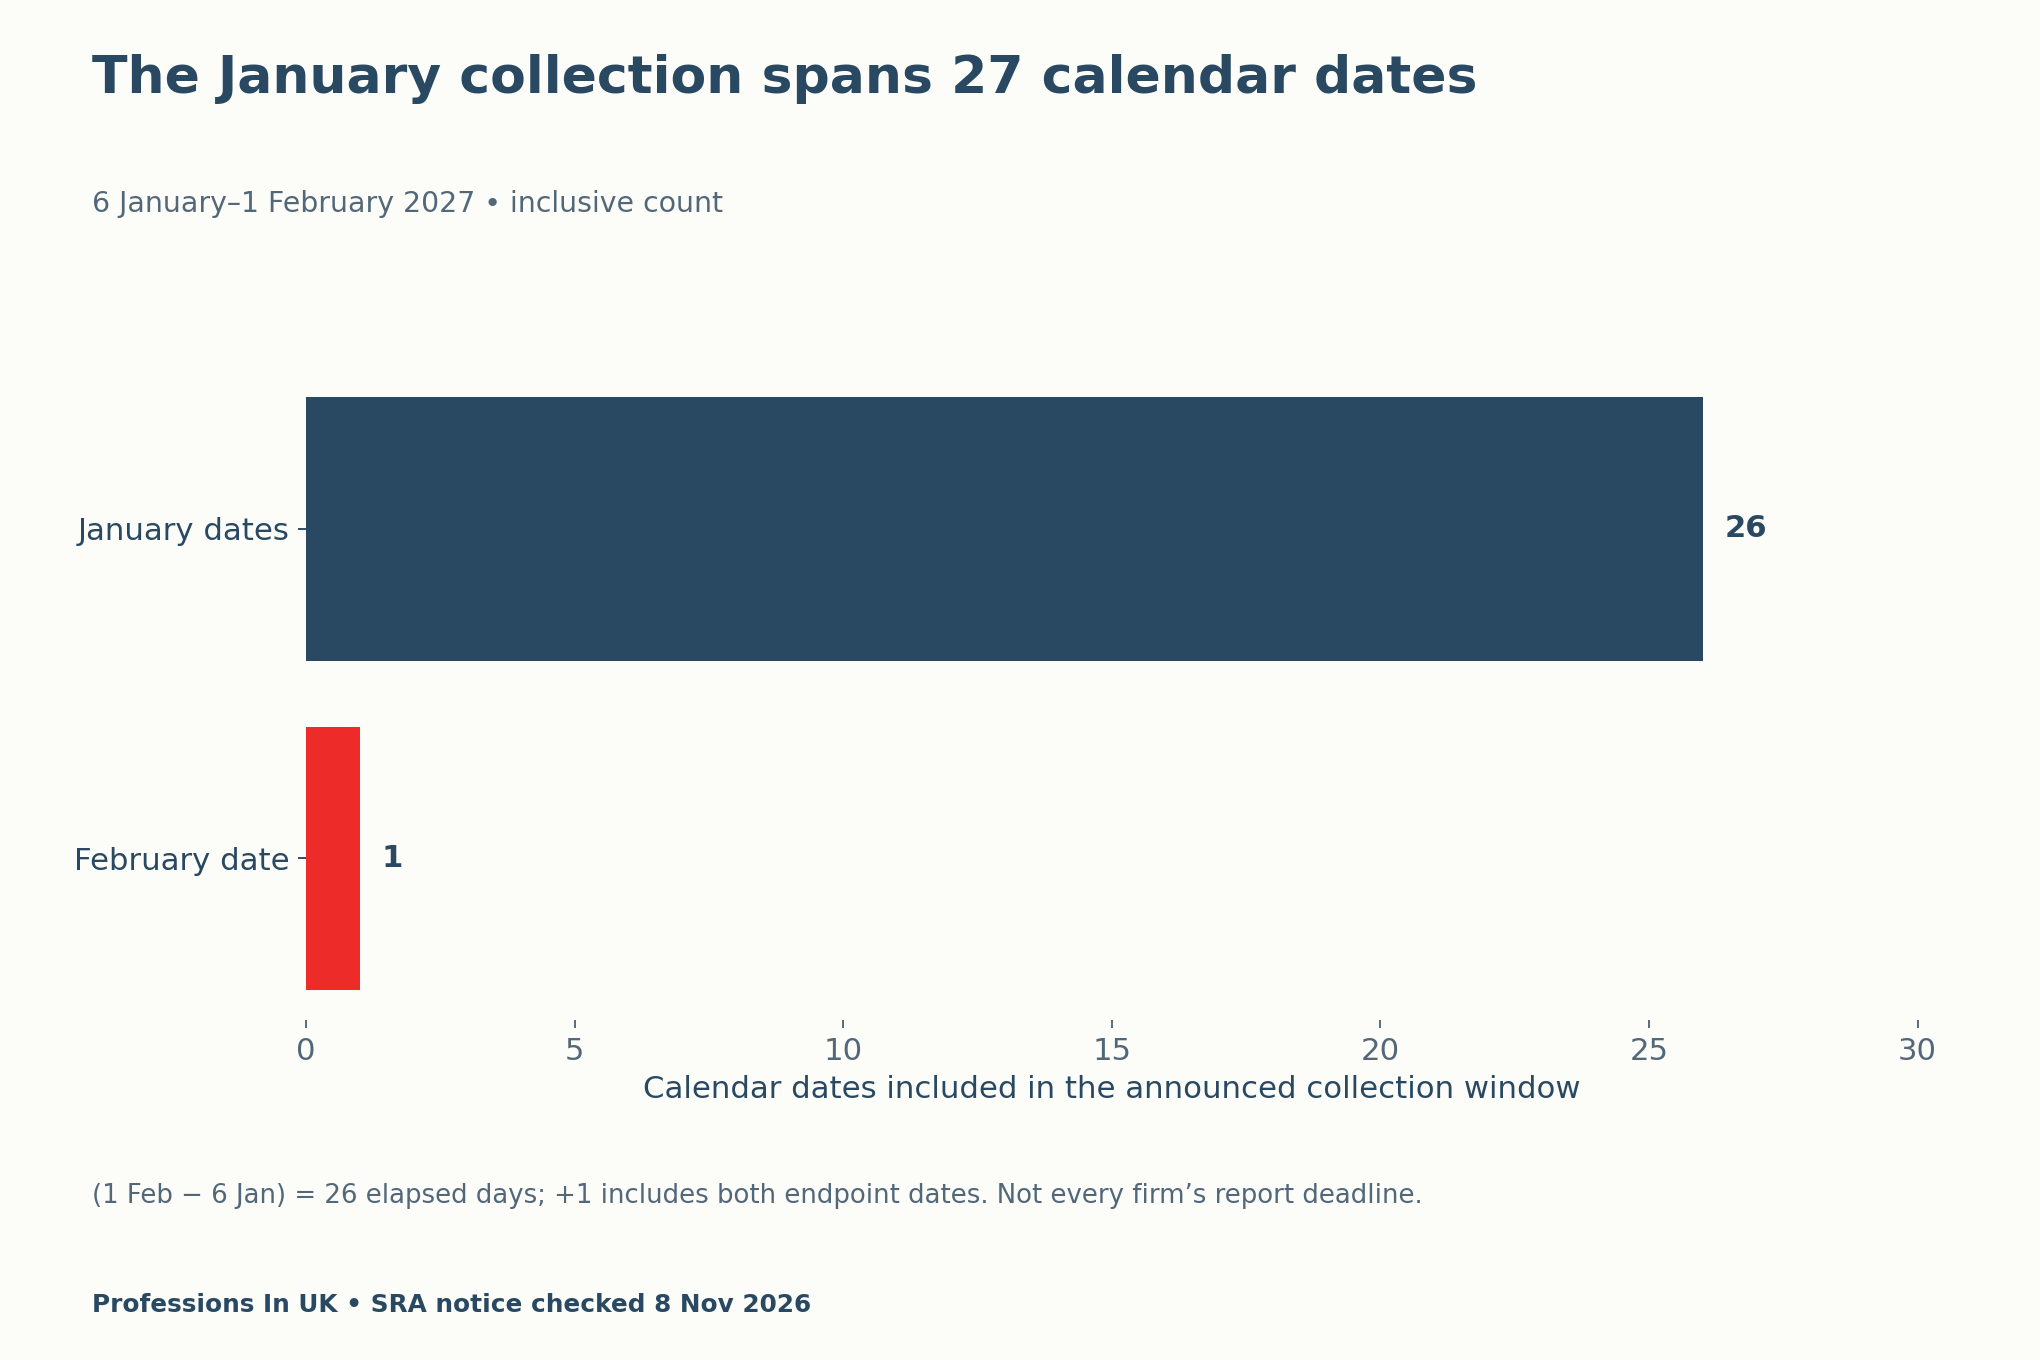
The SRA’s 5 November 2026 notice sets the collection window at 6 January to 1 February 2027. That covers 27 calendar dates when both endpoints count. It is not a single accountant-report deadline for every firm. This dated readiness guide explains the evidence and handoffs without deciding a firm’s exemption or compliance position.
Research checked on 8 November 2026 for England and Wales. Further SRA guidance on report submission and exemptions is still expected. Use the current regulator instructions and an appropriately qualified professional when applying them to a particular firm.
What the November notice confirms
The current SRA accounting-period collection notice announces a new report-submission regime from 1 April 2027. Its opening summary covers both qualified and unqualified reports for firms holding client money. However, the same notice says some firms may be exempt and promises more detail. Read those statements together; do not turn the opening summary into an unconditional rule for every circumstance.
| Milestone | Announced date | What it means |
|---|---|---|
| Accounting-period collection opens | 6 January 2027 | Provide accounting-period information through the announced form |
| Collection closes | 1 February 2027 | End of the announced initial collection window |
| Existing qualified-report process | Reports due before 31 March 2027 | The notice says to continue the current process |
| New report regime starts | 1 April 2027 | Check further submission and exemption guidance |
Count the January window without changing its meaning
There are 26 elapsed days between 6 January and 1 February. Adding one includes both endpoint dates, giving 27 calendar dates. January contributes 26 of those dates and February contributes one. This arithmetic describes the announced availability window; it does not create an extra grace period or determine the deadline for a firm’s report.
A useful internal calendar therefore needs distinct entries. One concerns this collection. Another concerns the firm’s actual accounting period and any applicable reporting obligations. If dates are unclear, record the question for the responsible reviewer. Avoid replacing a firm-specific deadline with the public January window.
SRA accountants reports 2027 checklist: separate the roles
The notice names three role categories that can complete the January form: authorised signatory, compliance officer for financial administration and compliance officer for legal practice. These are alternative eligible roles, not three required submissions. The SRA says it will contact those individuals and share the reporting-site link when the window opens.
Preparation can involve other colleagues. A legal cashier might assemble period records and identify gaps, for example. That preparatory contribution does not itself create authority to submit. Agree a named reviewer and an actual authorised submitter instead of leaving the task with an undefined “finance team”.
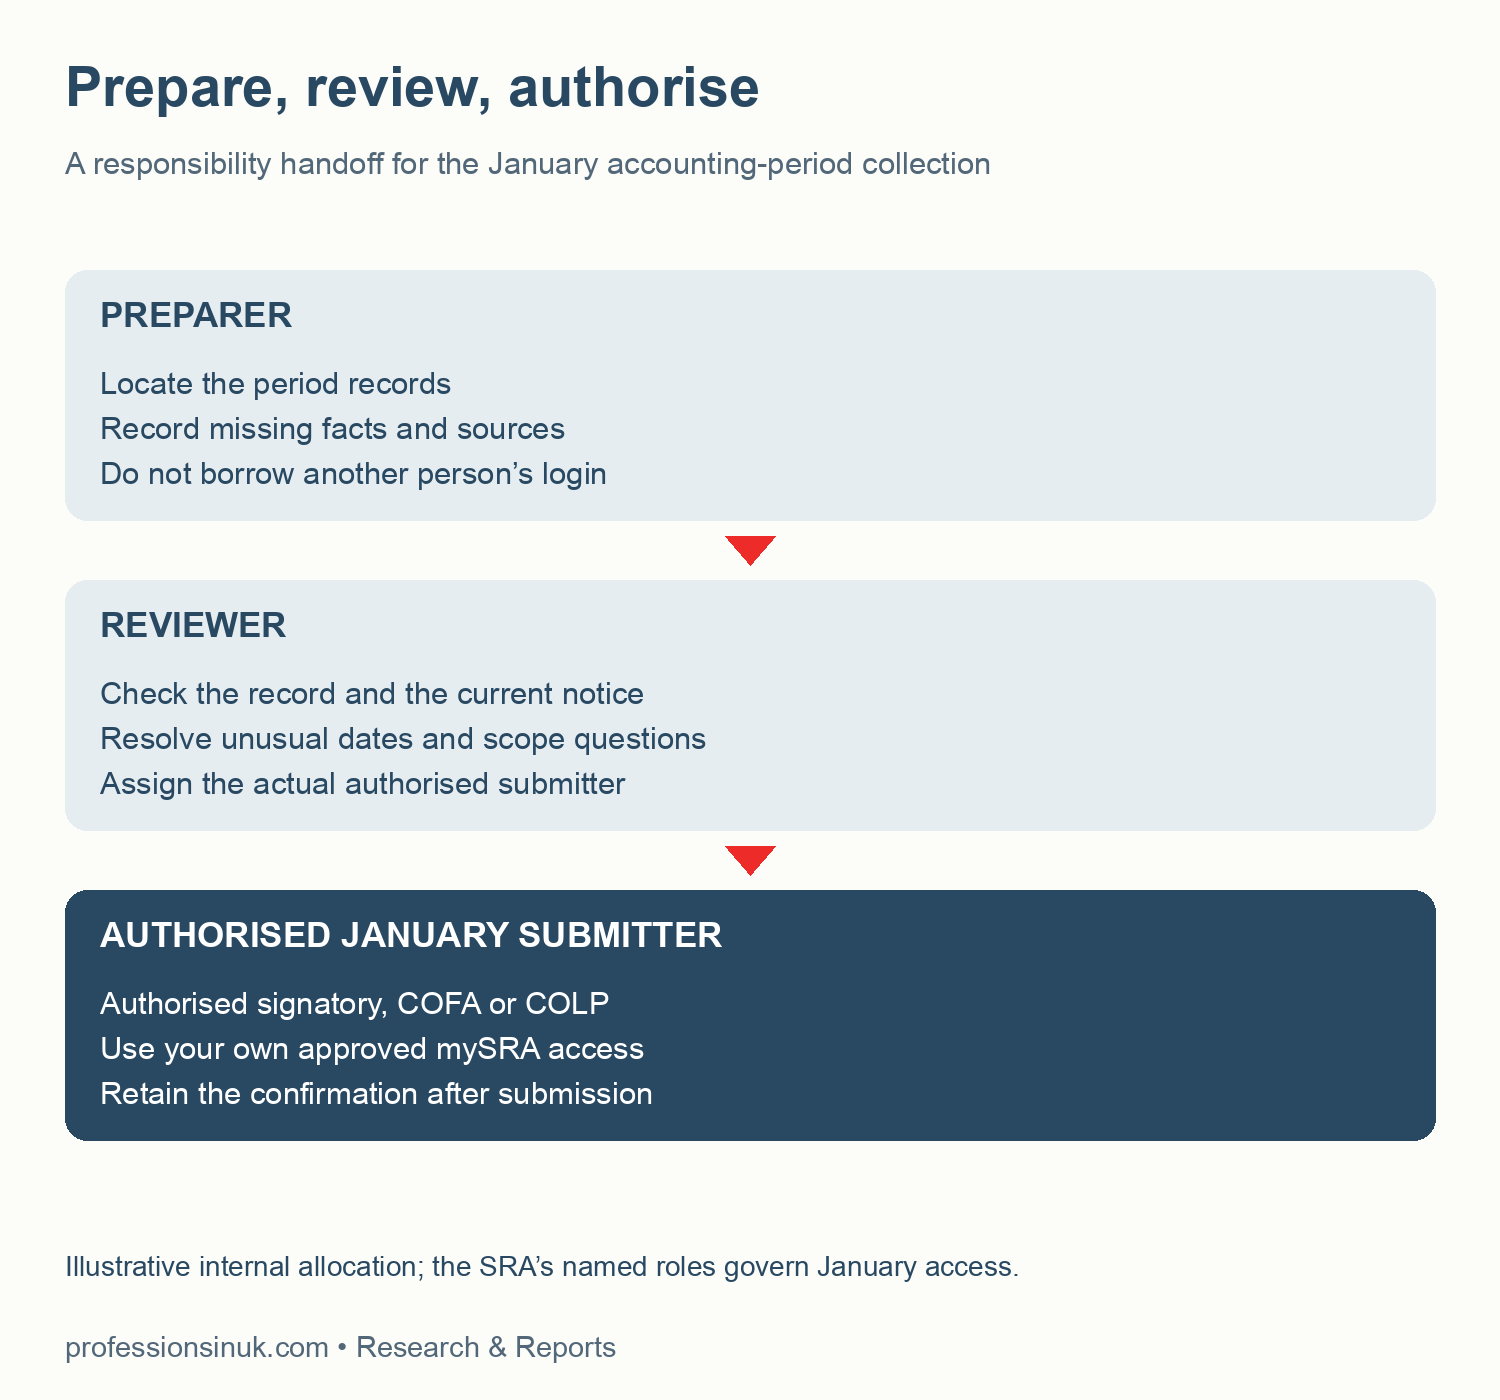
Use your own approved access. Do not borrow a colleague’s mySRA login, record passwords in a worksheet or circulate authentication codes. The notice asks the person who will report to check their authenticator arrangements. Account recovery or an authentication change should follow the SRA’s official process, handled by the account holder.
Locate the accounting-period evidence
The current notice first asks whether the firm still holds client money. If it does not, the cessation date matters. It says firms that ceased holding before 1 November 2026 will not need to do anything further in this collection. Keep that collection-specific statement separate from any other reporting duties.
For firms still holding client money, or holding it for any length of time after 1 November 2026, the notice asks whether a full accounting period or a cease-to-hold period has been completed. It then asks for the start and end of the last or current period. Check the live questionnaire when it becomes available, rather than copying a stale summary into a working instruction.
Retain the record supporting each date and flag any uncertainty. A useful handoff identifies the record’s location, its version and the unresolved question. It does not require client names, bank details or confidential balances in a shared research template. Keep actual firm evidence within the firm’s authorised systems.
Review unusual periods rather than automate a verdict
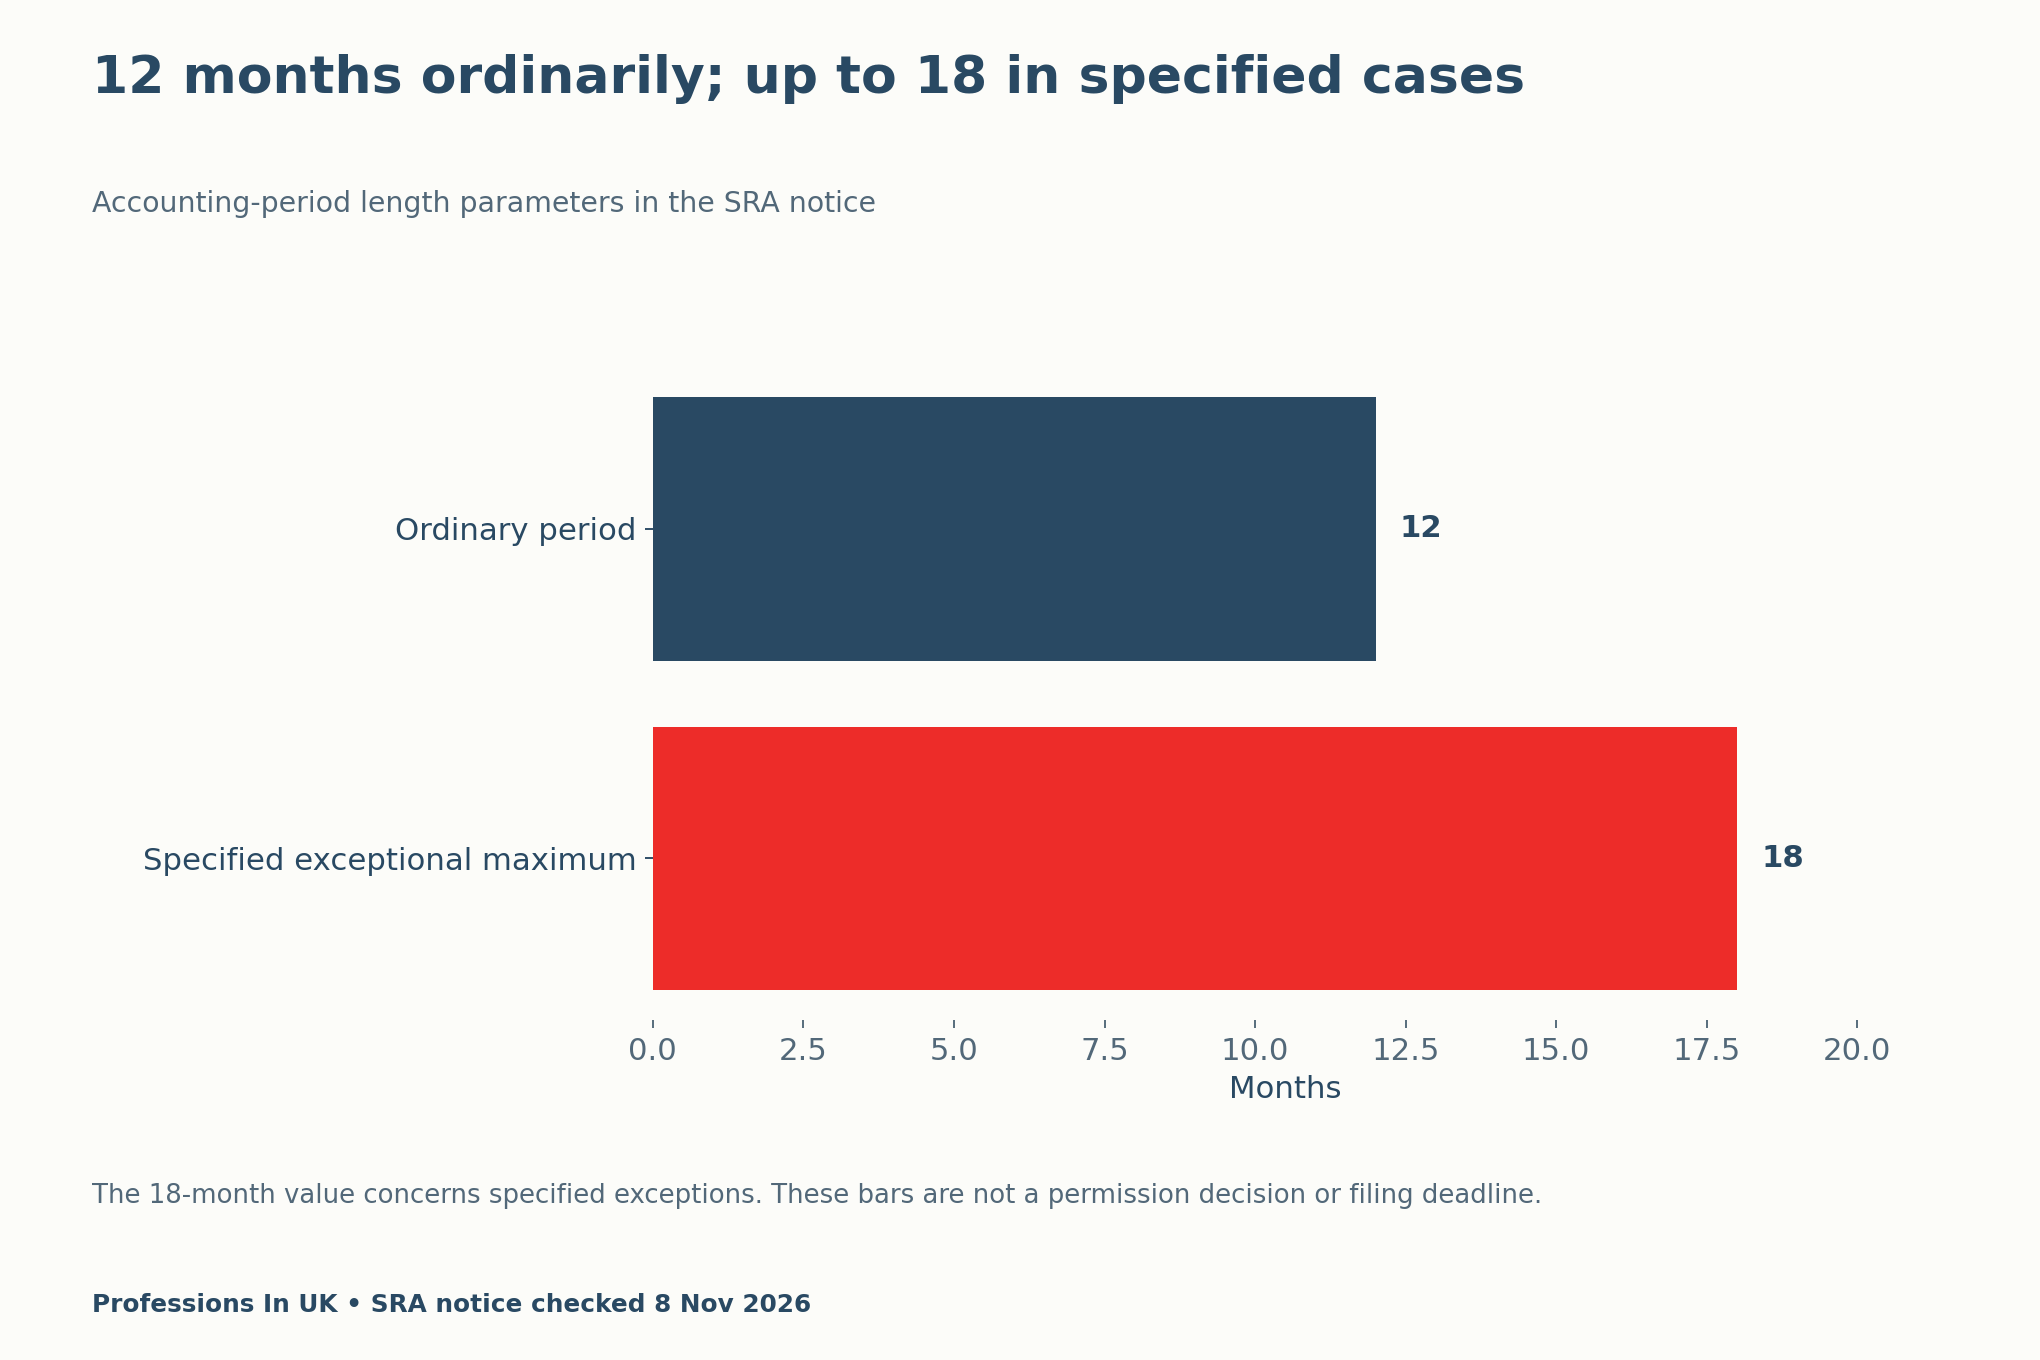
The notice describes a 12-month accounting period ordinarily. It also allows specified variations connected with changing the usual period, a first report or a report after a break from practice, up to 18 months. The numbers alone do not decide whether a firm fits an exception. A short period is not automatically wrong, and an 18-month period is not automatically permitted.
The blank date-review worksheet records start and end dates, missing fields, reversed dates and unusual periods for professional review. It deliberately contains no automatic exemption or compliance formula. If you add spreadsheet formulas, use them to highlight a date question, then document the qualified reviewer’s reasoning separately.
Keep the existing process and future guidance distinct
For qualified reports due before 31 March 2027, the notice directs firms to the existing accountant-report process. The current Accounts Rules provide the wider regulatory context. Neither a readiness worksheet nor a chart should replace the applicable rules or settle an individual transitional case.
Personalized UK Career Consulting
Receive tailored career guidance designed just for you. Get actionable steps and expert support to boost your career in 1-3 days. Take control of your career now.
Get StartedAfter the February collection, the SRA says it will explain what firms should do next and how to submit reports. It also promises exemption information. Put these open points in a guidance register with an owner and a future check date. Do not fill an unpublished operational detail with an assumption about a portal, declaration or report deadline.
For professional development, retain evidence of your actual role: records assembled, checks completed and questions escalated. Our skills-evidence guide explains how to describe a practical contribution without overstating authority or inventing a credential.
Download the SRA accountants reports 2027 checklist
The source-data file preserves dates, units and qualifications. The other three files are blank planning tools for handoffs, date review and unresolved guidance questions. They contain no completed firm audit and no credentials. Assign roles locally and keep confidential supporting records in approved systems.
- SRA dates and parameters with source notes (CSV)
- Preparation, review and authorised-handoff worksheet (CSV)
- Blank accounting-period date-review worksheet (CSV)
- Further-guidance questions register (CSV)
Methodology, limitations and citation
We transcribed the current 5 November SRA notice, retained its future dates and calculated the inclusive January window using ordinary calendar subtraction. Three charts describe separate date and period parameters. Further statistical charts would imply evidence that the notice does not contain. No firm was audited, no submissions were made and no compliance rate was measured.
The source is a dated regulator notice, not a workforce survey or a prediction of demand for legal-finance jobs. Detailed submission and exemption instructions remain to follow. Have an appropriately qualified professional apply current rules to a firm’s facts. These planning tools do not certify compliance or replace professional judgement.
Suggested citation: Professions In UK (8 November 2026), “SRA Accountant’s Reports 2027: A Readiness Checklist”, using the SRA’s accounting-period collection notice dated 5 November 2026. Preserve the distinction between the January collection and April commencement when reusing the dates.


